No Doc Mortgage
in California
★ ★ ★ ★ ★
- Alt Doc Loan Program
- Good for Self-Employed
- Foreign National Loan Program
- Purchase & Refinance Options
- Office Located in Los Angeles
What type of property are you refinancing?
Single Family
Multifamily
Condominium
Townhouse
How will this property be used?
Primary Residence
Vacation Home
Investment Property
Estimate credit score
Excellent 770+
Good 660-719
Avg. 620-659
Below avg. 580-619
Poor <579
What type of property are you purchasing?
Single Family
Multifamily
Condominium
Townhouse
Are you a first-time home buyer?
Yes
No
How will this property be used?
Primary Residence
Vacation Home
Investment Property
Estimate credit score
Excellent 770+
Good 660-719
Avg. 620-659
Below avg. 580-619
Poor <579
Final Step
By clicking "Get My Quote" you certify that you read and completely agree with the Privacy Policy
Summary
| Description | Information | Quantity | Price |
|---|---|---|---|
| Discount : | |||
| Total : | |||


No Doc Mortgage
in California
★ ★ ★ ★ ★
- Alt Doc Loan Program
- Stated Income Home Loans
- Good for self-employed
- Foreign National Loan Program
- Purchase & Refinance Options
- Office Located in Los Angeles
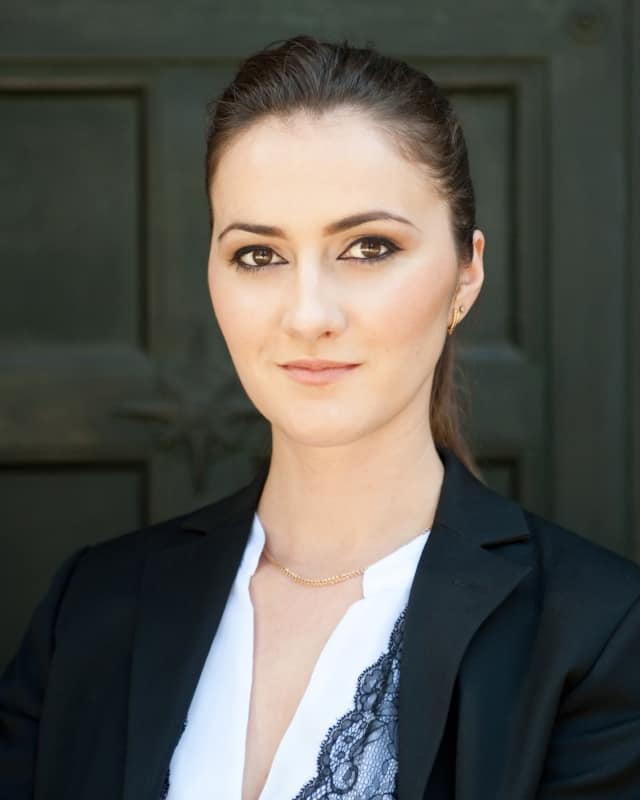
Irina Dyakun, CEO
What type of property are you refinancing?
Single Family
Multifamily
Condominium
Townhouse
How will this property be used?
Primary Residence
Vacation Home
Investment Property
Estimate credit score
Excellent 770+
Good 660-719
Avg. 620-659
Below avg. 580-619
Poor <579
What type of property are you purchasing?
Single Family
Multifamily
Condominium
Townhouse
Are you a first-time home buyer?
Yes
No
How will this property be used?
Primary Residence
Vacation Home
Investment Property
Estimate credit score
Excellent 770+
Good 660-719
Avg. 620-659
Below avg. 580-619
Poor <579
Final Step
By clicking "Get My Quote" you certify that you read and completely agree with the Privacy Policy
Summary
| Description | Information | Quantity | Price |
|---|---|---|---|
| Discount : | |||
| Total : | |||
Get Pre-Qualified for a No Doc Home Loan
If you’re self-employed or your income doesn’t fit traditional W-2 guidelines, a “no doc” mortgage may help you qualify using alternative documentation. In many cases, borrowers can use bank statements, verified assets, or other approved documentation instead of tax returns.
ID Mortgage Broker helps self-employed borrowers compare alternative-documentation options based on their income records, assets and property plans.
Start with a consultation to review which programs may fit and what supporting documents a lender would require. Eligibility remains subject to program guidelines and underwriting.
What is a No Documentation Loan?
“No doc” usually means alternative documentation, not “no verification.” Some programs don’t require tax returns or W-2s. But lenders still review proof of ability to repay.
Common options include:
- 12–24 months bank statements
- Asset-based qualification
- Investment property programs (when eligible)
Rates and down payments are often higher than conventional loans.
No Doc Mortgage Loans Have Obvious Benefits
1. Require less documentation
2. Available to self-employed and foreign nationals who don’t need to show their tax returns
3. Competitive rates and terms
Have Questions? Reach us out.
In-Person at LA Office
16200 Ventura Blvd, Unit 324 Encino, CA 91436
Cell-phone
M-F 10 AM-5 PM (PST)
On-line
Simply e-mail or use online-chat
No Doc (Alt-Doc) Loan Requirements in California
Income or Asset Records
Have your available bank statements, business records or asset statements ready to discuss. Your loan officer will confirm the documents and history needed for a suitable program.
Property and Loan Purpose
Know the property location, estimated value and loan amount. Explain whether you are buying or refinancing and whether you will live in the home or rent it out.
Down Payment or Equity
Estimate your available down payment or current equity, plus funds for closing costs. Ask whether the program also requires reserves after closing.
Credit and Debts
Have a summary of monthly debt payments ready, and tell your loan officer about credit issues that may affect your options.
Which No Doc Loan Option Fits Your Situation?
The right path depends on how you earn income, the assets you can document and how you will use the property. Ask which of these options fits your scenario; documentation and availability vary by lender.
Bank Statement Programs
If you are self-employed, ask whether personal or business bank statements can be used to document qualifying income. Confirm which deposits, business expenses and statement history the lender will review.
Asset-Based Programs
An asset-based review may suit borrowers with substantial eligible assets. Ask which accounts count, how access to funds is verified and how funds needed for closing or reserves affect qualification.
Rental Property / DSCR
For a rental investment, ask whether a DSCR program can assess the property’s rent against its loan payments. Tell your loan officer if you plan to live in the property, because occupancy affects the financing options. Explore DSCR loans in California.
Other Income Documentation
If bank statements or assets do not fit your situation, ask whether another documentation method is available. An employment letter or profit-and-loss statement may need supporting records; neither guarantees approval.
No-Doc Mortgages in California — FAQ
What does “no doc loan” mean in California?
In most cases, “no doc” is shorthand for a loan with less traditional paperwork. It usually means you may not need to provide W-2s or full tax returns, but the lender will still review other documents to confirm you can repay the loan.
Is a no doc loan the same as a bank statement loan?
Not always. A bank statement loan is one common type of no doc style program, especially for self-employed borrowers. “No doc” is a broader term that can also include asset-based options or other alternative documentation programs.
Can I qualify without W-2 income?
Not having W-2 wages is different from having no way to repay. A lender may assess documented business income, eligible assets or qualifying rental income, depending on the loan and property use. A no-doc label does not mean automatic approval or no financial review.
How do I compare loan offers?
Ask for comparisons using the same loan amount, property use and term. Review the interest rate, APR, points, lender fees, cash needed to close and any prepayment penalty. A simpler documentation route may cost more; compare the full terms before choosing.
Are no doc loans available for foreign nationals?
Some lenders consider foreign-national scenarios. Ask about identity, residency-status and source-of-funds documentation rather than assuming a no-doc label removes these checks. Tell your loan officer where you live, how you earn income and how the property will be used so they can confirm whether a suitable program is available.
What down payment is usually required?
There is no single down-payment requirement for every alt-doc loan. The amount depends on the lender, documentation method, property use and your financial profile. For a refinance, ask about required equity instead. Request a quote that identifies down payment or equity, closing costs and any reserve requirements.
Can a no doc loan be used for a primary residence?
Ask about a program that specifically allows owner occupancy if you plan to live in the home. Bank-statement or asset-based qualification and rental-property DSCR financing are not interchangeable. Explain whether the property will be your primary residence, second home or rental before comparing options.
GET IN TOUCH
OUR BUSINESS LOCATION
FOLLOW US
